News
Nigeria at 66: What Tinubu inherited, what he changed, what Nigerians gained

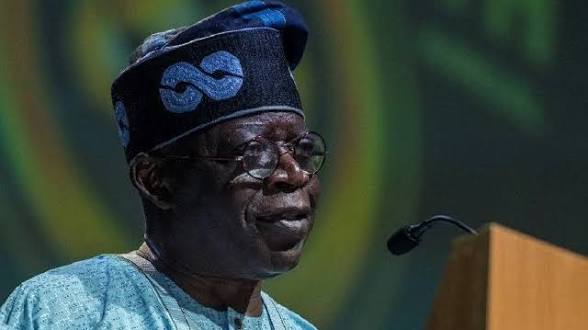
As Nigeria marks 66 years of independence on October 1, the country enters another year of nationhood with an economic story that is increasingly defined by one word: Transition. Blueprint.ng reports.
Over three years ago when President Bola Ahmed Tinubu assumed office, the administration’s reforms have fundamentally altered the way Nigeria managed fuel pricing, foreign exchange, public revenue, investment and infrastructural development.
The changes have not been painless
Tinubu inherited an economy battling expensive petrol subsidies, multiple exchange rates, foreign-exchange shortages, weak revenues, rising debt-service obligations and declining investor confidence.
His administration responded with the removal of petrol subsidy, exchange-rate liberalisation, tighter monetary policy, tax and revenue reforms and an aggressive infrastructural development programme.
The immediate consequences were severe; Petrol prices jumped, the naira depreciated sharply, borrowing costs rose and households and businesses faced higher transportation, food, energy and imported-input costs.
But by 2026, evidence of macroeconomic stabilisation has become more visible.
Nigeria’s real GDP expanded by 4.43 per cent year-on-year in the second quarter of 2026, up from 3.89 per cent in the first quarter, according to the National Bureau of Statistics. Growth was supported by both oil and non-oil sectors.
The International Monetary Fund has also credited the reforms with improving macroeconomic outcomes, strengthening external buffers and improving the functioning of the foreign-exchange market.
The subsidy shock and the fiscal reset
Perhaps no decision symbolises Tinubu’s economic agenda more than the May 2023 removal of petrol subsidy.
The policy immediately transferred a large part of the cost of petrol from government to consumers, triggering an unprecedented rise in fuel prices.
But the government argues that subsidy reform released resources for infrastructure and other public priorities.
According to government figures, N6.47 trillion was spent on strategic infrastructure between June 2023 and December 2025, with highways accounting for more than half. The Lagos-Calabar Coastal Highway alone received N2.23 trillion, while N1.11 trillion went to the Sokoto-Badagry Superhighway.
For Lagos economist and Chief Executive Officer of the Centre for the Promotion of Private Enterprise, Muda Yusuf, the reforms have produced measurable gains in government revenues, reserves, foreign-exchange stability, trade and investor confidence.
But Yusuf insists that stability must now become productivity.
His argument is that macroeconomic stability is a means, not an end, and must ultimately produce stronger businesses, employment, incomes and living standards.
That distinction remains crucial. The economic statistics may be improving, but millions of Nigerians still judge the economy by food prices, transport fares, rent, electricity bills and purchasing power.
Naira finds firmer ground
The second major reset was the dismantling of the multiple-exchange-rate system.
The initial consequences included a sharp depreciation of the naira and higher import costs. However, the IMF says exchange-rate reforms have helped improve market functioning and rebuild external buffers.
The administration’s reform programme has coincided with a substantial improvement in the country’s external position, while inflation has also moderated from its 2024 peak.
Former World Bank Vice-President Dr Obiageli Ezekwesili has acknowledged progress in stabilising the foreign-exchange market, attributing the relative stability of the naira to the government’s move towards market-driven forex policies.
Economists, however, caution that short-term currency movements should not be confused with permanent stability.
Investment banker and stockbroker Tajudeen Olayinka has linked improved capital-market performance to stronger corporate results and investor expectations, while analysts have urged policymakers to ensure that the gains become broader and sustainable.
Stock market becomes reform scoreboard
One of the clearest financial-market indicators of changing investor sentiment has been the Nigerian Exchange.
When Tinubu assumed office in 2023, market capitalisation stood at about N30 trillion. By August 2026, the Nigerian Exchange Group told the president that it had risen to N160 trillion.
The Finance Minister and Coordinating Minister of the Economy, Taiwo Oyedele, attributed the market’s expansion to economic reforms, describing the capital market as an increasingly important avenue for wealth creation.
The NGX Chairman, Umaru Kwairanga, told the president that a $1 trillion Nigerian capital market was achievable, arguing that the country possesses the human and material resources required to reach that ambition.
The figures nevertheless represent market capitalisation, not money distributed directly to households. For most Nigerians, the more important question is whether stronger markets translate into jobs, investment and lower business costs.
From reform to roads
The economic reset has also been accompanied by an infrastructure push unprecedented in scale under the current administration.
The Presidency says more than 2,700 kilometres of highways and major roads are under construction, reconstruction or rehabilitation. They include the Lagos-Calabar Coastal Highway, Sokoto-Badagry Superhighway, Abuja-Kaduna-Zaria-Kano Road and East-West Road.
The Lagos-Calabar Coastal Highway has emerged as the flagship. Its first 30-kilometre completed segment was commissioned in 2025, while financing for subsequent sections has been secured.
The Federal Government also approved more than N7 trillion in additional major road and bridge contracts in 2026, including the Lagos-Calabar extension, reconstruction of Carter Bridge in Lagos and another section of the Sokoto-Badagry corridor.
Infrastructure Concession Regulatory Commission Director-General, Dr Jobson Ewalefoh, has argued that macroeconomic reforms are creating the conditions for long-term private-sector participation in infrastructure.
According to him, investor confidence, fiscal stability and clearer market signals are critical for attracting private capital into roads, airports, energy, ICT and other infrastructure.
The administration’s PPP programme has consequently expanded into aviation, power, maritime infrastructure, healthcare and digital governance.
Lagos and the energy transition
The reform agenda is also increasingly visible in transportation and energy.
In May 2026, Tinubu commissioned four CNG infrastructure projects in Lagos, Abuja and Owerri, including the Portland Gas CNG Mother Station at Ojota, Lagos, designed to expand domestic gas utilisation and provide an alternative to petrol-dependent transportation.
Power remains one of the biggest tests. The government says it is clearing legacy obligations, expanding transmission infrastructure and promoting renewable energy and decentralised electricity systems.
Manufacturers: Gains still come with pain
Manufacturers remain among the biggest beneficiaries—and casualties—of the reform transition.
Manufacturers Association of Nigeria Director-General Segun Ajayi-Kadir described the period as a “difficult but consequential economic transition”.
He has acknowledged the need to correct longstanding distortions but warned that manufacturers have faced a disproportionate burden from fuel costs, exchange-rate adjustments, electricity tariffs and expensive credit.
Yusuf shares that concern, arguing that the next phase must focus squarely on productivity.
The challenge is particularly urgent because lower inflation does not mean lower prices. It means prices are rising more slowly.
What Nigerians gained and what remains
The gains are increasingly measurable: stronger external buffers, improved forex-market functioning, rising GDP, higher government revenues, a dramatically larger stock market, renewed infrastructure investment and growing interest from domestic and international investors.
But the costs are equally measurable
The IMF estimates that poverty remains high, while millions of Nigerians continue to face food insecurity. The World Bank has similarly warned that macroeconomic stabilisation has yet to fully translate into improved household welfare.
At 66, Nigeria has moved from a period of economic distortion and crisis towards a new policy framework built around market pricing, fiscal reform, investment and infrastructure.
The defining question for the country’s 67th year is whether those foundations can produce the dividend that matters most to ordinary Nigerians: more jobs, cheaper and reliable energy, productive industries, efficient transport networks, stronger incomes and greater purchasing power.


“She wants me to stop talking against husband snatchers” — Rita Edochie speaks as she appears in court over the ₦1bn lawsuit filed against her by Judy Austin

“If a man h!ts you once, he will do it again. Value your life and leave” — Rick Ross’ ex-girlfriend Jazzma Kendrick accuses him of ph¥sical ass@ult

Ugochinyere hails APP victory in Yobe LGA poll, says party steadily expanding

FCMB Group Flags Potential 60-Day Q3 Results Delay as Bank Undergoes Interim Audit
âA man can sleep with 30â40 women and still marry, but a woman can sleep with 7â10 men and be rejectedâ â Veteran actor Chiwetalu Agu

Nigeria @66: Defence minister charges on unity, security

Prolonged absence: Tinubu sued for refusing to hand over power

“A man can sleep with 30–40 women and still marry, but a woman can sleep with 7–10 men and be rejected” — Veteran actor Chiwetalu Agu
-

 Special Reports1 day ago
“She wants me to stop talking against husband snatchers” — Rita Edochie speaks as she appears in court over the ₦1bn lawsuit filed against her by Judy Austin
- Special Reports2 days ago
“If a man h!ts you once, he will do it again. Value your life and leave” — Rick Ross’ ex-girlfriend Jazzma Kendrick accuses him of ph¥sical ass@ult
- News2 days ago
Ugochinyere hails APP victory in Yobe LGA poll, says party steadily expanding
- Finance3 days ago
FCMB Group Flags Potential 60-Day Q3 Results Delay as Bank Undergoes Interim Audit