News
Hyping The IPO: Dangote Refinery Worth N493, Not N525 – GTI Report

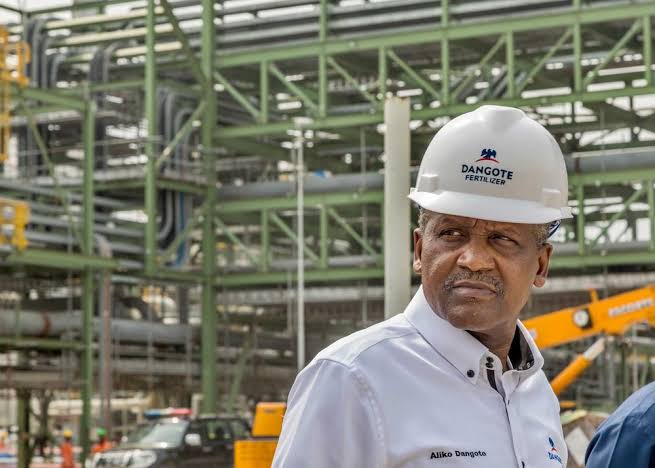
● IPO Over Priced? 22-page valuation report details why the Refinery’s worth is N32 Below IPO Price
Fresh valuation concerns have trailed Africa’s largest-ever share sale as GTI Research has placed the fair value of Dangote Petroleum Refinery and Petrochemicals at N493 per share, below the N525 offer price at which the company is selling shares to the public.
The verdict is contained in a 22-page valuation report by GTI Research analysts led by Mr. Abiodun Ogunniyi, published on Wednesday, September 16, 2026, as the N2.15 trillion IPO remains open for subscription through October 13, 2026.
According to GTI, its probability-weighted fair value stands at approximately N493 per share, meaning the current offer sits above both the firm’s central estimate and its base case.
The report explicitly labels the offer as “FULLY VALUED,” attributing the premium to what it calls “that unearned premium,” implying that the pricing already reflects much of the refinery’s future growth rather than just its current earnings power.
GTI’s valuation range, which reflects genuine uncertainty about how the refinery’s economics will evolve, spans a wide spectrum: Conservative case at N328, Base case at N503, and Bull case at N640.
The debate comes as the refinery, which processes 700,000 barrels per day and reported $1.82 billion after-tax profit in H1 2026 against a $476 million loss in 2025, is seeking to raise about $1.6 billion through 4.1 billion ordinary shares to fund its expansion to 1.4 million barrels per day.
READ ALSO
After NOP NIGERIA Report, Oil Ministry Director Queried, Minister Disowns Claim
How Dangote Refinery’s IPO Pulled N1.5 Trillion In Just 60 Minutes
‘Not Your Children’s School Fees, Don’t Sell Your House,’ Sanusi Lists Money You Must Not Use To Buy Dangote Refinery IPO
Dangote Offers Jobs To LASU First-class Graduates, Pledges ₦600m Girls’ Hostel
‘Not My Priority;’ Dangote Speaks On Business Empire Without A Son To Carry On His Name
Other independent analysis reviewed by Nairametrics also flags pricing pressure. A mid-cycle check using refining margins of $15-$18 per barrel, a 6-7x exit multiple and 12-15% discount rate produces a fair value range of N176-N324, well below N525, suggesting the valuation can be justified only if earnings remain materially above a normalized industry cycle.
The recent private placement provides a useful benchmark. A $2.5 billion placement for a 6% stake in June-July implied an equity value of about $41.7 billion and roughly N473 per share, making the IPO an 11% premium to that institutional transaction.
GTI’s conclusion lands amid scarcity arguments that could still support the share price post-listing. With only 3.3% free float and NGX capitalization at about N160 trillion, the refinery could represent about 29% of the enlarged market, potentially forcing benchmark funds and pension assets to seek exposure.
But as the GTI report warns, scarcity is not the same as value. Investors may see technical demand lift the stock on listing day, but long-term returns will depend on utilization, margins, free cash flow, taxation, expansion execution and borrowing for the planned $12.8 billion capacity doubling.
NOP NIGERIA








2027: Governors, APC membership can’t assure election victory – Turaki

ONSA, DSS, Police rescue 8 kidnap victims in Kaduna

28 states approve State Police Bill as National Assembly prepares to transmit to Tinubu

Kidnappers abduct two visually impaired individuals in Plateau

How Obasanjo’s Threat Forced Me to Flee Nigeria for Ghana – Amaechi

Osun NBA calls for digital improve, repairs for courts

Nigerian lady exhibits off fashionable outfit she wore to her husband’s wedding ceremony to his third spouse (video)

Policemen lose their lives following assault by bandits in Zamfara
-

 Politics3 days ago
2027: Governors, APC membership can’t assure election victory – Turaki
-
 News3 days ago
ONSA, DSS, Police rescue 8 kidnap victims in Kaduna
- Breaking3 days ago
28 states approve State Police Bill as National Assembly prepares to transmit to Tinubu
- Politics3 days ago
Kidnappers abduct two visually impaired individuals in Plateau